Walk into any insurance broker's office in Lagos and ask for "business insurance," and you will get a blank stare followed by a dozen questions. That is because there is no single policy called business insurance. There is fire cover, public liability, group life, marine cargo, and half a dozen other products, and the right combination depends entirely on what your business does, where it operates, and what it owns.
Most entrepreneurs skip insurance not because they do not see the value, but because the process of choosing feels confusing and the fear of buying the wrong thing keeps them from buying anything at all. This guide walks through exactly how to choose, step by step, so you end up with cover that matches your actual risk rather than a generic package a salesman pushed on you.
Step 1: List What You Actually Stand to Lose
Before you speak to any insurer, sit down and list the things that would hurt your business badly if they went wrong. Be specific. If you run a boutique with ₦4 million in stock, that stock is an asset at risk from fire, flooding, or theft. If you run a consulting firm with no physical inventory but client contracts worth millions, your risk is different, it is more about liability and professional errors than physical assets.
Write down three categories: physical assets (stock, equipment, fittings, vehicles), people risk (employees, their safety, your legal duty to them), and liability risk (customers, visitors, or clients who could sue you). This list becomes the map for which policies you actually need.
Step 2: Check What Nigerian Law Requires of You
Some insurance is not optional. If you employ five or more people, group life insurance is a legal requirement under the Pension Reform Act, and it must cover at least three times each employee's annual salary. If your business operates commercial vehicles, third party motor insurance is mandatory under the Insurance Act. If you are in construction, employers' liability cover is often required before a contractor can even bid for public sector work.
Knowing your legal minimums first prevents you from either skipping something you are required to have, which exposes you to regulatory penalties, or overspending on optional cover before the compulsory ones are settled.
Step 3: Match Policies to Your Risk List
Once your risk list and legal requirements are clear, match them to specific products.
If you have physical stock or equipment, look at fire and burglary insurance, sometimes called fire and special perils. This protects against fire, lightning, explosion, and theft with forced entry. If you are in a flood prone area like parts of Lagos Island or Port Harcourt during rainy season, ask specifically whether flood is included or needs to be added.
If customers or visitors enter your premises, public liability insurance covers injury or property damage claims against you. A restaurant, salon, gym, or retail shop should treat this as close to essential.
If you have five or more staff, group life insurance is not a choice. Get quotes from at least two insurers and compare the multiple of salary covered and the claims process.
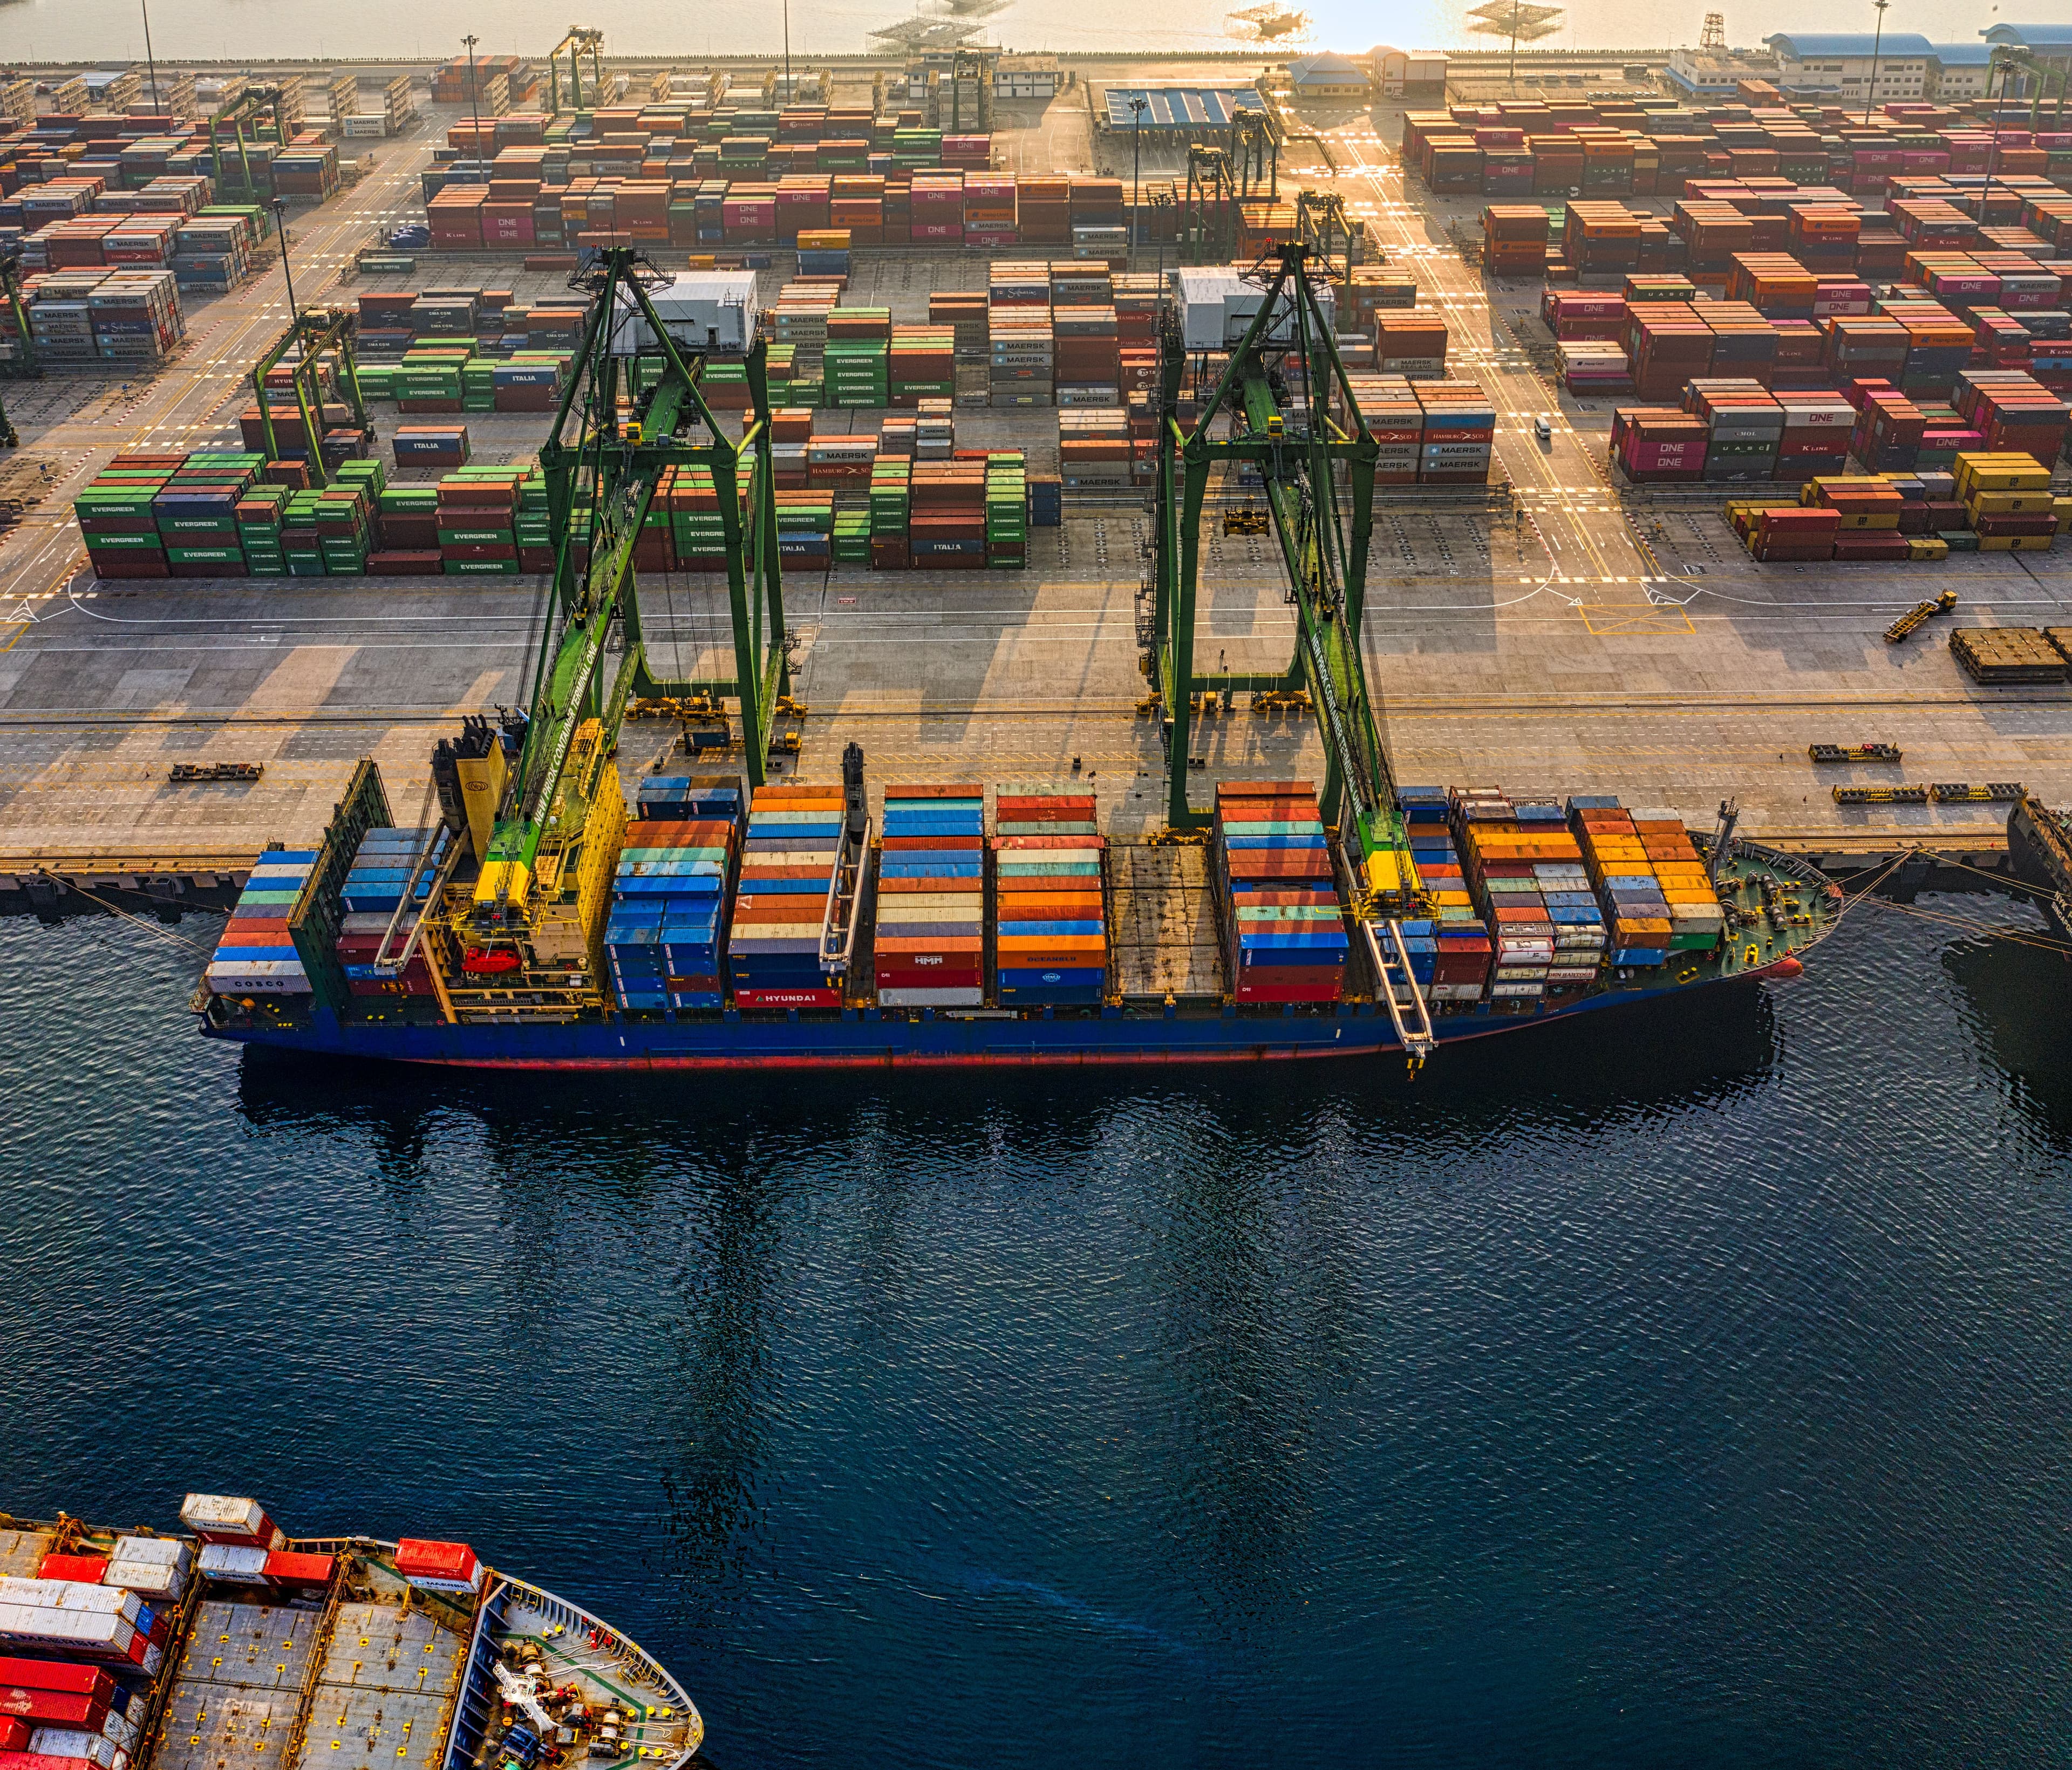
If you import or export goods, marine cargo insurance covers loss or damage while your goods are in transit, whether by sea, air, or road. This matters even for small importers bringing in a single container of goods through Apapa port.
If your income depends on continuous operation, ask about business interruption cover as an add on to your fire policy. This replaces lost income if an insured event forces you to shut down temporarily.
Step 4: Get Quotes From at Least Three Sources
Do not accept the first quote you receive. Approach at least two or three licensed insurers or brokers and compare not just the premium, but the coverage limits, exclusions, and excess (the amount you pay out of pocket before the insurer covers the rest). A cheaper premium with a high excess and narrow coverage can cost you more in the long run than a slightly higher premium with better terms.
Working through a registered insurance broker rather than going direct to one insurer often gets you better comparison, since brokers are required to shop your risk across multiple insurers rather than push one company's product.
Step 5: Verify the Insurer Is Licensed by NAICOM
Before you pay a single naira in premium, confirm the insurer is registered with the National Insurance Commission. NAICOM maintains a public list of licensed insurers and brokers. This single check protects you from the handful of unlicensed operators who collect premiums and disappear when a claim comes in. Ask for the insurer's NAICOM registration number directly and cross check it.
Step 6: Read the Exclusions Before You Sign
Every policy document has a section listing what is not covered. This is the part most people skip and the part that matters most when a claim is denied. Common exclusions include damage from unmaintained equipment, losses during periods where premiums were unpaid, and specific perils like flood or riot that require separate add ons. Ask your broker to walk you through the exclusions in plain language before you sign anything.
Step 7: Set a Reminder to Review Annually
Your business changes every year. Stock levels grow, you hire more staff, you move to a bigger space. A policy bought two years ago at your old inventory level may leave you underinsured today. Set a calendar reminder to review your coverage limits against your current business size every year at renewal time.
Getting This Right the First Time
Choosing insurance does not need to be complicated once you separate it into what you risk, what the law requires, and what actually matches your business. Start with the legally required policies, add the ones that protect your biggest physical or liability exposure, and build from there as your business grows. The businesses that regret buying insurance are rare. The ones that regret not buying it are common, and by then it is too late to fix.